Working with a claims adjuster
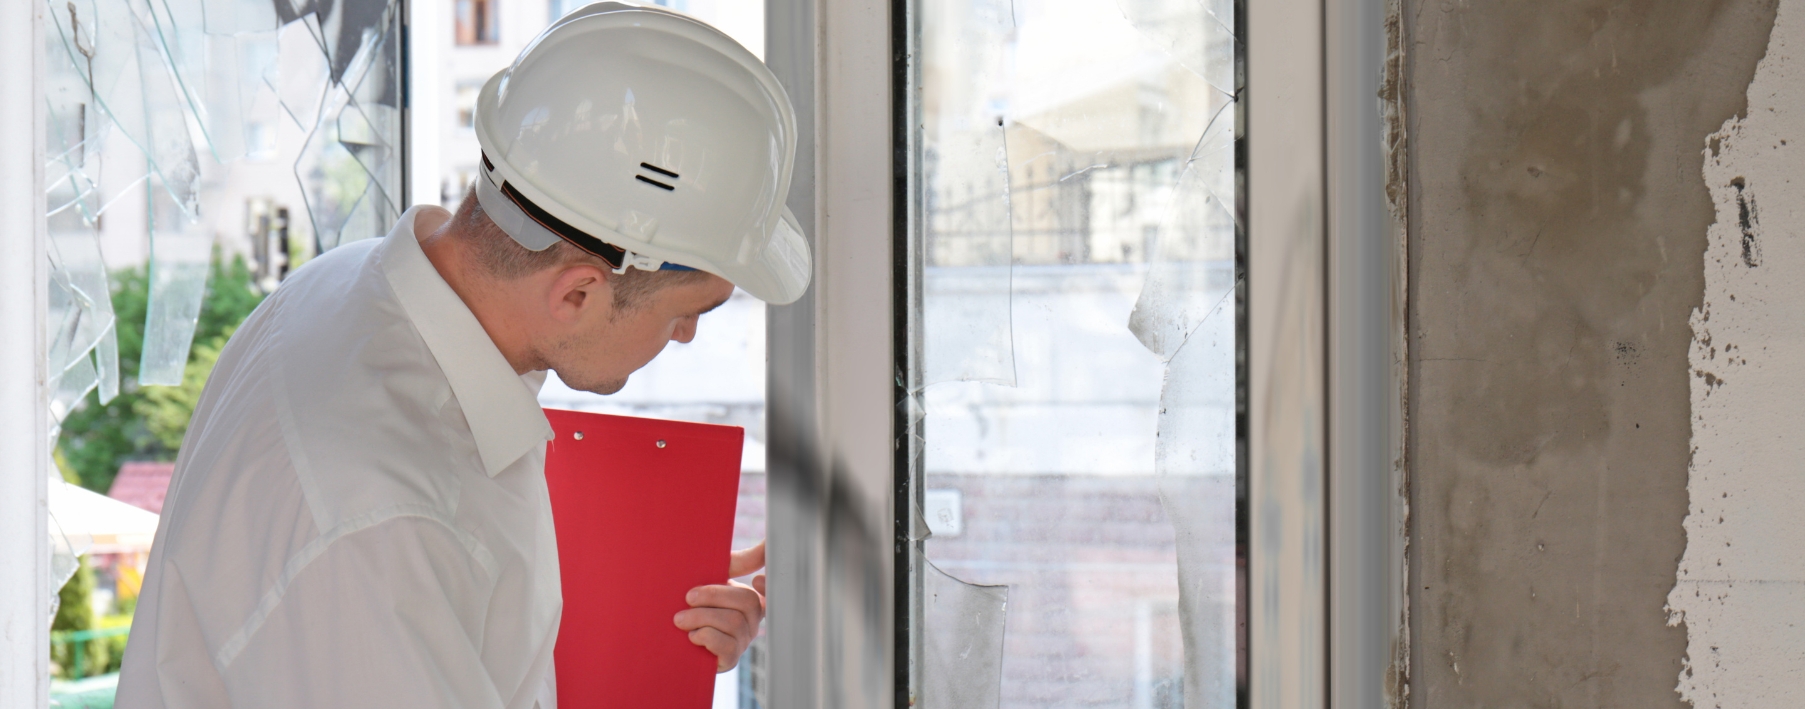
A claims adjuster is the person your insurer sends to inspect the damage, decide what your policy covers, and put a number on the repair. Their report is what your settlement is based on. And that raises a couple important questions: Who does your adjust actually work for? And how much say do you have in your settlement number?
There are three types of adjusters and who pays them tells you whose interests they represent. In this article we explore what the adjuster does, how they reach a settlement number, and what you can do to prepare for their inspection.
Key takeaways
- Know which type of adjuster you're dealing with—insurance-company affiliated, independent, and public adjusters are each paid by different people, which we’ll explain
- Document damage before repairs start—get photos and video of damage as soon as possible, and save receipts for any immediate repairs or material you spent money on; that’s what your estimate gets built from
- Your policy sets the math—your limits and deductible play a big role in determining your settlement
- You can dispute the first offer—if your settlement doesn’t seem right, you can present more evidence or get a second opinion
- Maintenance is the part you control, upkeep keeps small problems from turning into claims
What a claims adjuster does and how they make decisions
Evaluating liability
A claims adjuster investigates your claim to determine what your insurer owes under your policy. They decide whether the damage is covered and what your insurer should pay for it. An adjuster examines the damage, speaks with you and any witnesses, and even reviews police reports when relevant. They not only check the damage, they make sure the damage fits the definitions written into your policy.
During the visit, stick to the facts of the damage. That keeps the conversation focused and avoids misunderstandings about how the incident happened.
Calculating the settlement
Once coverage is confirmed, the adjuster calculates the settlement based on your policy terms, estimating the cost of materials and labor needed for repairs. If you're reviewing home insurance deductibles to see which one fits your home, remember that the adjuster's math runs on your policy limits and deductible, and the final number is reduced by any applicable depreciation if your policy pays actual cash value rather than replacement cost. Their report is the document your payout is based on.
Example
For instance, let’s say there’s a storm and a tree falls on your home, damaging the roof. You contact your insurance company to file a claim under your homeowners insurance policy for the repairs, and an insurance claims adjuster is assigned to your claim.
So, what does a claims adjuster do in this case?
They will likely visit your home to take photos of the fallen tree and any resulting damages. They will take notes and may request a statement from you; if the tree originally came from someone else’s property, they may even take a statement from that property owner or any witnesses.
Your insurance claims adjuster will then use this and other information to evaluate your claim, including determining coverage and settlement amount according to your policy coverage terms and limits. Once a determination of coverage is made, you’ll be notified and the adjuster will go over any repair options with you. If repairs have already been done to your property and your loss is covered, your adjuster may coordinate payment up to your coverage limits, minus any applicable deductible.
If you don’t agree with the adjuster’s determination, they can also help guide you through the steps of a dispute. In some cases, there may be an insurance adjustment, and your settlement offer may change. Other times, your claim might be escalated to another adjuster or department who will review it and make their own determination.
The three types of adjusters you might work with
- Company adjusters—these are paid employees of your insurance company, who handle your claim according to your insurers standards
- Independent adjusters—contractors working for third-party firms, brought in when claim volume runs high after a hurricane or other catastrophe; they still represent your insurer's interests
- Public adjusters—independent adjusters you hire and pay yourself; a public adjuster serves your interests rather than the insurer’s; paid a percentage of the settlement
How to prepare for an adjuster’s inspection
Here are four steps you can take to prepare for an inspection and help ensure your claims process goes smoothly.
- Document everything by taking clear photos and videos of the damage before any temporary repairs begin.
- Create a detailed inventory of damaged personal items, including estimated ages and original purchase prices. Good documentation helps prevent disagreements on your settlement offer.
- Keep receipts for all emergency mitigation efforts, such as tarping a roof or water removal services.
- Be present during the inspection to answer questions and point out specific areas of concern that the adjuster might miss.
Insurance claims adjusters and advances in technology
These days, available technology can make an insurance claims adjuster’s job easier. This technology can be utilized to help evaluate claims, manage information, identify data patterns, and determine loss values.
For example, adjusters may use technology such as drones to photograph damages to your home, such as viewing a high roof after a wind storm. Today’s insurance claims adjuster software can also help manage homeowners insurance claims faster and generate more accurate loss estimates. Some programs even use AI to facilitate claims processing around the clock.
Proactive steps to avoid future claims
Hippo helps you avoid having to file a claim in the first place.
In a newly built home, that means watching for problems that tend to show up in the first few years, like foundation settlement issues or water intrusion. You can nip these problems in the bud by staying on top of maintenance and regularly checking the spots where water accumulates.
Keeping up with maintenance does more than help you avoid claims. In fact, it's one of the few things you can do to lower your overall risk profile from an insurer’s perspective.
For instance, if you manage a larger property or shared common areas, running a facility audit is one way to find maintenance gaps before they turn into losses. Should you need to file a natural disaster claim, a documented history of property care makes the paperwork easier. And knowing how to file a claim correctly from the start keeps your records in order.
What to do first when filing a claim
- Review your policy to understand your specific limits and deductibles.
- Download a property damage checklist so you don't miss the damage that isn't obvious.
- Contact your insurance agency immediately to start the filing process.
If you think your settlement offer is inadequate or doesn't cover the true cost of repairs, talk to a professional contractor or a public adjuster for a second opinion.
After your claim closes, there’s one more “to do” you’ll want to put on the calendar: an annual review of your policy when it renews. That's a good time to compare home insurance rates from other carriers and check that your limits still match what your home would cost to rebuild today.
If you insure a vehicle too, check which carriers let you bundle home and auto insurance when you’re pulling quotes. For questions about other insurance options, like pet insurance, talk to your Hippo agent. We’re here to help. Reach us at (650) 426-0546 or [email protected].
And remember, you can compare quotes from 70+ carriers in about 60 seconds at hippo.com
Frequently asked questions
Do I have to accept the first offer from an adjuster?
You don't have to accept the first settlement offer from an adjuster. You can negotiate the settlement or send additional evidence if the initial estimate falls short of your repair costs.
Does a claims adjuster work for me?
A claims adjuster usually works for your insurance company, either as a salaried employee or independent contractor. You can also hire a public adjuster who works independently and serves your interest. Either way, adjusters are bound by the terms of your policy and by state regulations to assess the damage fairly.
How long does an inspection take?
The length of an inspection depends on how much damage there is and how large your property is. Ask the adjuster when they schedule the visit, so you can plan to be there for it.
What does an insurance claims adjuster look for?
An insurance claims adjuster’s job is to gather information about a claim, document reports and evidence, analyze policy coverage, and calculate loss estimates to determine a policyholder’s settlement offer. In order to do this, claims adjusters will look at the actual damage, any related reports or statements, relevant receipts and records, and typical repair or replacement costs.
How much does an insurance claims adjuster cost?
Insurance claims adjusters who work for or on behalf of the insurance carrier are assigned to claims at no cost to policyholders. If you decide to hire a public adjuster to help navigate and negotiate a claim, however, their fee can be as much as 20% of the total settlement amount.
Can an insurance claims adjuster deny a claim?
Based on the information gathered about a claim, relevant coverage, and the details surrounding a loss, an insurance claims adjuster can recommend to the carrier that a claim be denied. Ultimately, the decision rests with the insurance company, and policyholders can always dispute these findings. You can also hire a public adjuster to represent you if your claim is denied or you feel that the settlement amount is insufficient.
How long does it take for an insurance claim to be adjusted?
An insurance claim can take anywhere from a few days to multiple weeks to be investigated and a determination made. There are state specific laws and regulations that determine the time periods.
What may insurance claims adjusters ask?
An insurance claims adjuster’s job is to investigate a claim and help determine coverage, which involves asking questions about the loss and how it occurred. For property damage claims, they may also ask questions about your property, including any previous work or repairs that may have been done.
This article is for informational purposes only and was compiled from sources not affiliated with Hippo. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.
Sources cited are publicly available and referenced in August, 2026.