Filing a homeowners insurance claim is stressful enough without trying to figure out what happens next at every stage. This guide walks you through the Hippo claims process from start to finish; what to do first, what an adjuster looks for, how payments work, and what to do if something goes wrong.
Timelines and coverage vary by policy and state, so treat this as a practical process map rather than a guarantee of any specific outcome.
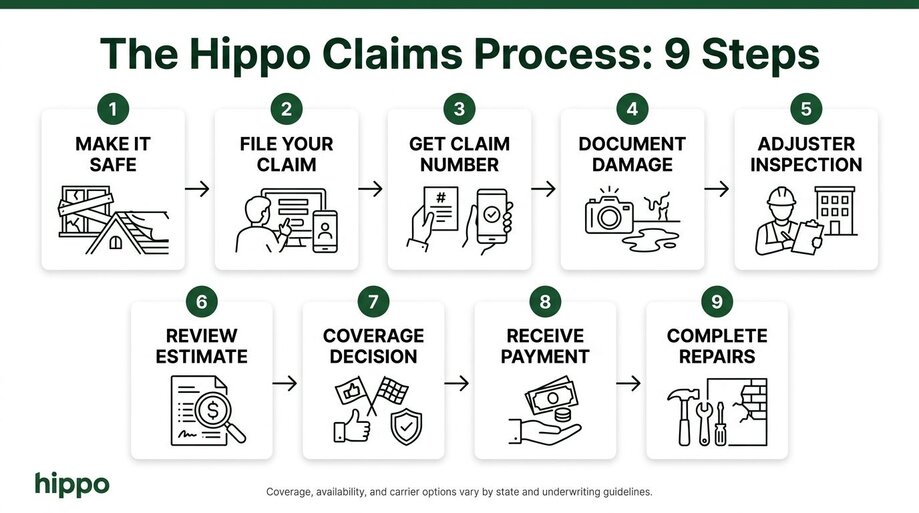
At a glance: The Hippo claims process (step-by-step)
Here’s what typically happens from the moment you have a loss to the time your claim closes:
Step 1: Make the situation safe and prevent more damage
Turn off water at the main shutoff, board up broken windows, tarp a damaged roof section. Stopping further damage is your immediate priority, and reasonable mitigation costs are typically reimbursable.
Step 2: Start your claim and get a claim number
File through Hippo’s official channel (app, online portal, or phone). You’ll receive a claim number that tracks everything from this point forward.
Step 3: Complete intake
A claims representative will gather the date and time of the loss, the cause, the affected rooms and systems, and your contact details.
Step 4: Document the loss
Photograph and video everything before any cleanup. List damaged items, including serial numbers for electronics and appliances. Keep every receipt for emergency expenses.
Step 5: Schedule the inspection
Hippo’s team will arrange for an inspection of the property. Be available, give access to all affected areas, and walk through the damage together if possible.
Step 6: Review the coverage decision
Once the adjuster completes the scope of loss, our claims team reviews your policy including any applicable endorsements and exclusions to determine what's covered.
We'll let you know what falls under your deductible and explain how your settlement is calculated, whether by Replacement Cost Value (RCV) or Actual Cash Value (ACV), so you know exactly what to expect.
Actual Cash Value (ACV) means the insurer calculates the current depreciated value of the damaged property. A five-year-old roof is worth less than a new one, so ACV reflects that reduced value. Replacement Cost Value (RCV) means you’re reimbursed for the cost of replacing or repairing the damage with equivalent new materials, without deducting for age or wear. Many policies pay ACV initially and then release the withheld depreciation, called recoverable depreciation, once you provide proof that repairs are complete. If your policy is ACV-only, there’s no second payment; the first check is your settlement.
Step 7: Receive the estimate and dispute it if needed
You’ll get a written estimate of the covered loss. If your contractor’s estimate differs significantly from the insurer’s, you can request a re-inspection or submit a formal request to supplement the money you received.
Step 8: Receive payment if coverage afforded
Once the estimate is agreed, the carrier issues payment minus your deductible and less applicable depreciation. If your policy pays replacement cost value, you may receive an initial actual cash value payment first, with the withheld depreciation released after repairs are complete.
If your home has a mortgage, your lender is typically named as a loss payee on the policy. This means the insurer issues a check made out to both you and the lender. Your mortgage servicer will have its own process for endorsing the check and releasing funds in draws as repairs are completed. Contact them early because this step can add weeks if you’re not prepared.
Step 9: Complete repairs and close the claim
Work with your contractor to complete repairs. Submit proof of completion and paid invoices if your policy requires them to release withheld depreciation. Keep all documentation until the claim is fully closed.
Hippo claim timeline: what affects how long it takes
Simple claims with clear documentation can often move from filing to initial payment in a few weeks. More complex claims like large structural losses, significant personal property inventories, or claims that involve coverage disputes can take several months. Catastrophe events like regional storms or wildfires stretch timelines considerably because adjusters are handling many claims simultaneously and contractors are in short supply.
What speeds a claim: submitting complete documentation at the time of filing, providing easy and flexible access for inspections, working with a contractor who communicates clearly with the adjuster, and responding promptly when the claims team asks for additional information.
What slows a claim: missing photos or receipts that require follow-up requests, hard-to-schedule inspection appointments, disputes about coverage scope, estimate gaps between your contractor and the insurer, and unavoidable administrative delays during catastrophe periods.
Common mistakes that slow claims and how to avoid them
Don’t wait to file
Some policyholders delay filing while they assess the damage or wait for a contractor’s estimate. Most policies require you to report a loss within a certain window. File as soon as practical after the loss.
Don’t throw away damaged items before the adjuster sees them
Keep broken materials, damaged appliances, or ruined belongings in place until they can be inspected or until you get written permission to dispose of them. Photos alone may not be sufficient for high-value items.
Don’t skip the mitigation step
Failing to take reasonable steps to prevent additional damage after a covered loss can reduce what you’re entitled to receive. A small water leak that’s not contained can become a major mold remediation claim that becomes partially your responsibility.
Don’t sign over your claim rights to a contractor without understanding what you’re signing
Assignment of Benefits (AOB) agreements transfer your insurance rights to the contractor. AOB laws and restrictions vary by state, and some states limit or regulate how these agreements can be used. Read any contractor agreement carefully, and check with your state's Department of Insurance if you have questions about AOB rules where you live.
Frequently asked questions about the claims process
How do I file a claim with Hippo?
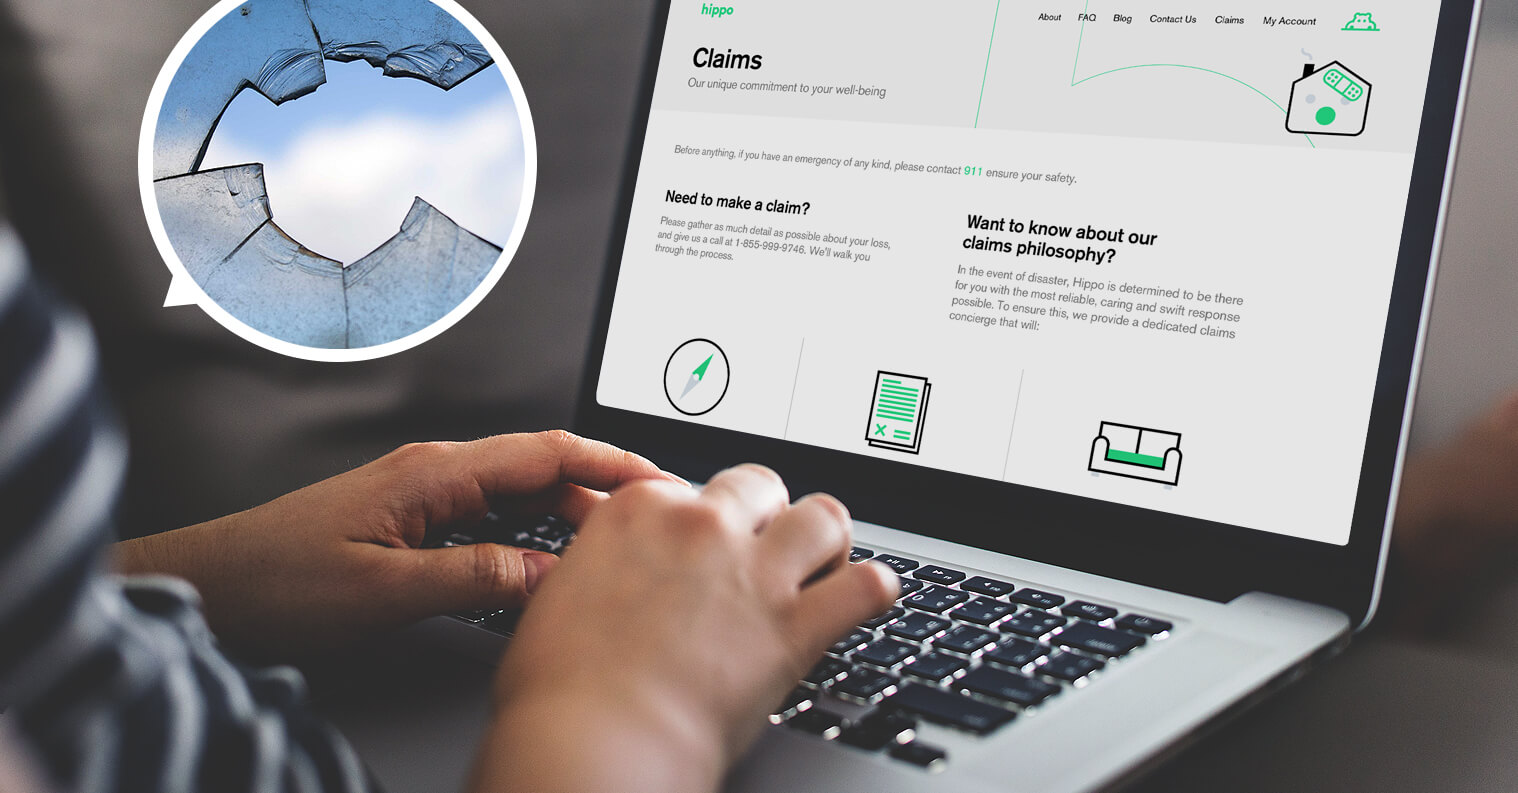
File through your Hippo account portal, the app (if available in your state), or call the claims number at (855) 999-9746 (also your policy declarations page). Your claim number is issued right after you submit. Have your policy number, loss date and cause, and a list of affected areas ready.
Fore more information, visit Hippo Claims.
How long does a Hippo claim take?
Timing varies widely. Small, well-documented claims can resolve in a few weeks. Complex structural losses or those involving coverage disputes can take months.
Most states mandate minimum acknowledgment and investigation windows, though specific requirements vary, check your state's insurance regulations or Department of Insurance for the exact timelines that apply to you.
Will someone be visiting my home?
For most significant structural claims, yes. Some smaller or straightforward claims may use a virtual inspection. Your claims adjuster will tell you what to expect for your specific situation.
Can I start repairs before the inspection?
Temporary repairs to prevent more damage are generally fine and often required. Permanent repairs should usually wait until after inspection or until you have explicit approval from your claims team so the original scope of damage can be properly documented.
What is a supplement?
A supplement is a formal request to add damage or costs that were not part of the original estimate. If your contractor finds hidden damage during repairs, they document it and submit a supplement to the insurer for review.
What if my claim is denied?
Request the denial in writing and review the exact policy language cited. You can submit additional evidence and request a re-review.
Will filing a claim raise my premium?
A claim may affect your renewal premium, though the impact depends on the claim type, your claim history, your state’s regulations, and your specific carrier. One large claim for a covered event typically has less impact than multiple smaller claims filed in quick succession.
Understanding the Hippo claims process before you need it can make the situation even more manageable. Document the damage thoroughly, file as soon as possible, keep every receipt, and communicate consistently with your claims contact. The more organized you are at each stage, the more control you have over the timeline and outcome.
This article is for informational purposes only. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.