What does homeowners insurance cover?
Homeowners insurance pays to repair or rebuild your home after a covered event, and it protects you against lawsuits if someone is injured on your property and decides to sue. What it doesn't pay for is the part people tend to learn the hard way, usually after a pipe bursts or a storm hits.
Your mortgage lender usually requires insurance to protect the asset behind your loan. And for you, it does more—such as standing between a liability claim and your savings. Knowing exactly where standard insurance stops is key to knowing where coverage gaps can arise and how you can close them.
Key takeaways
- A standard policy has six parts—three that rebuild property and three that cover liability—plus living expenses if you can’t live in your home due to a covered loss
- Insurance isn’t a maintenance plan—wear and tear, deferred upkeep, and pests lie outside most standard policies
- Floods and earthquakes require their own policy or rider—a standard policy excludes both
- Liability is worth serious consideration—it's the backstop that protects your savings from a liability claim
- Your declarations page is where to start—check your dwelling and liability limits against what rebuilding would cost today
The six parts of a standard homeowners policy
Standard homeowners insurance provides a financial safety net around the largest asset most people own—your home. When you compare home insurance rates, you’ll find that most policies are built from the same six components. Three of them rebuild property; three cover liability and living expenses if you have to move out of your home temporarily.
The three parts that rebuild property
- Dwelling—the core of the policy; It helps cover the costs to repair or rebuild the physical structure of your home if it's damaged by a covered event like fire or wind
- Other structures—buildings on your property that aren't attached to the house, such as detached garages, sheds, or fences
- Personal property—the things inside your home, such as furniture, electronics, and clothing; If they're stolen or destroyed, this part of the policy helps with replacement costs
The three parts that cover liability and living expenses
- Loss of use—if a covered event makes your home uninhabitable, this helps pay your additional everyday living expenses; think hotel bills and restaurant meals while your home is under repair
- Personal liability—this protects you if someone is injured on your property and sues you; it helps cover legal fees and court awards up to your policy limits
- Medical payments—limited help with a guest's medical bills after an injury at your home, regardless of who’s at fault; It’s designed to settle small claims quickly
What homeowners insurance doesn't cover
Insurance isn’t a maintenance plan. It responds to sudden, accidental events, not to the predictable results of time and wear. Knowing the difference is key to knowing which costs are yours to bear and which would be covered by your policy.
The maintenance gap
Standard policies typically don’t cover damage caused by deferred maintenance, normal wear and tear, or pest infestations like termites. If your roof leaks because it's twenty years old and due for replacement, the policy likely won't pay for a new roof. The same goes for aging appliances and corroded pipes. Upkeep of those items is your responsibility, which in some ways gives you a measure of control.
Many common maintenance mistakes among new homeowners trace back to routine inspections that never happened. Staying on top of seasonal maintenance is one of the more reliable ways to avoid losses that your policy won’t cover, yet fewer homeowners are keeping up with it.
In Hippo's 2026 Housepower Report, 38% of homeowners said they were satisfied with the maintenance they completed in 2025, down from 44% in 2024. Plumbing problems, appliance breakdowns, and system failures were the three most common issues reported that year.
Excluded natural disasters
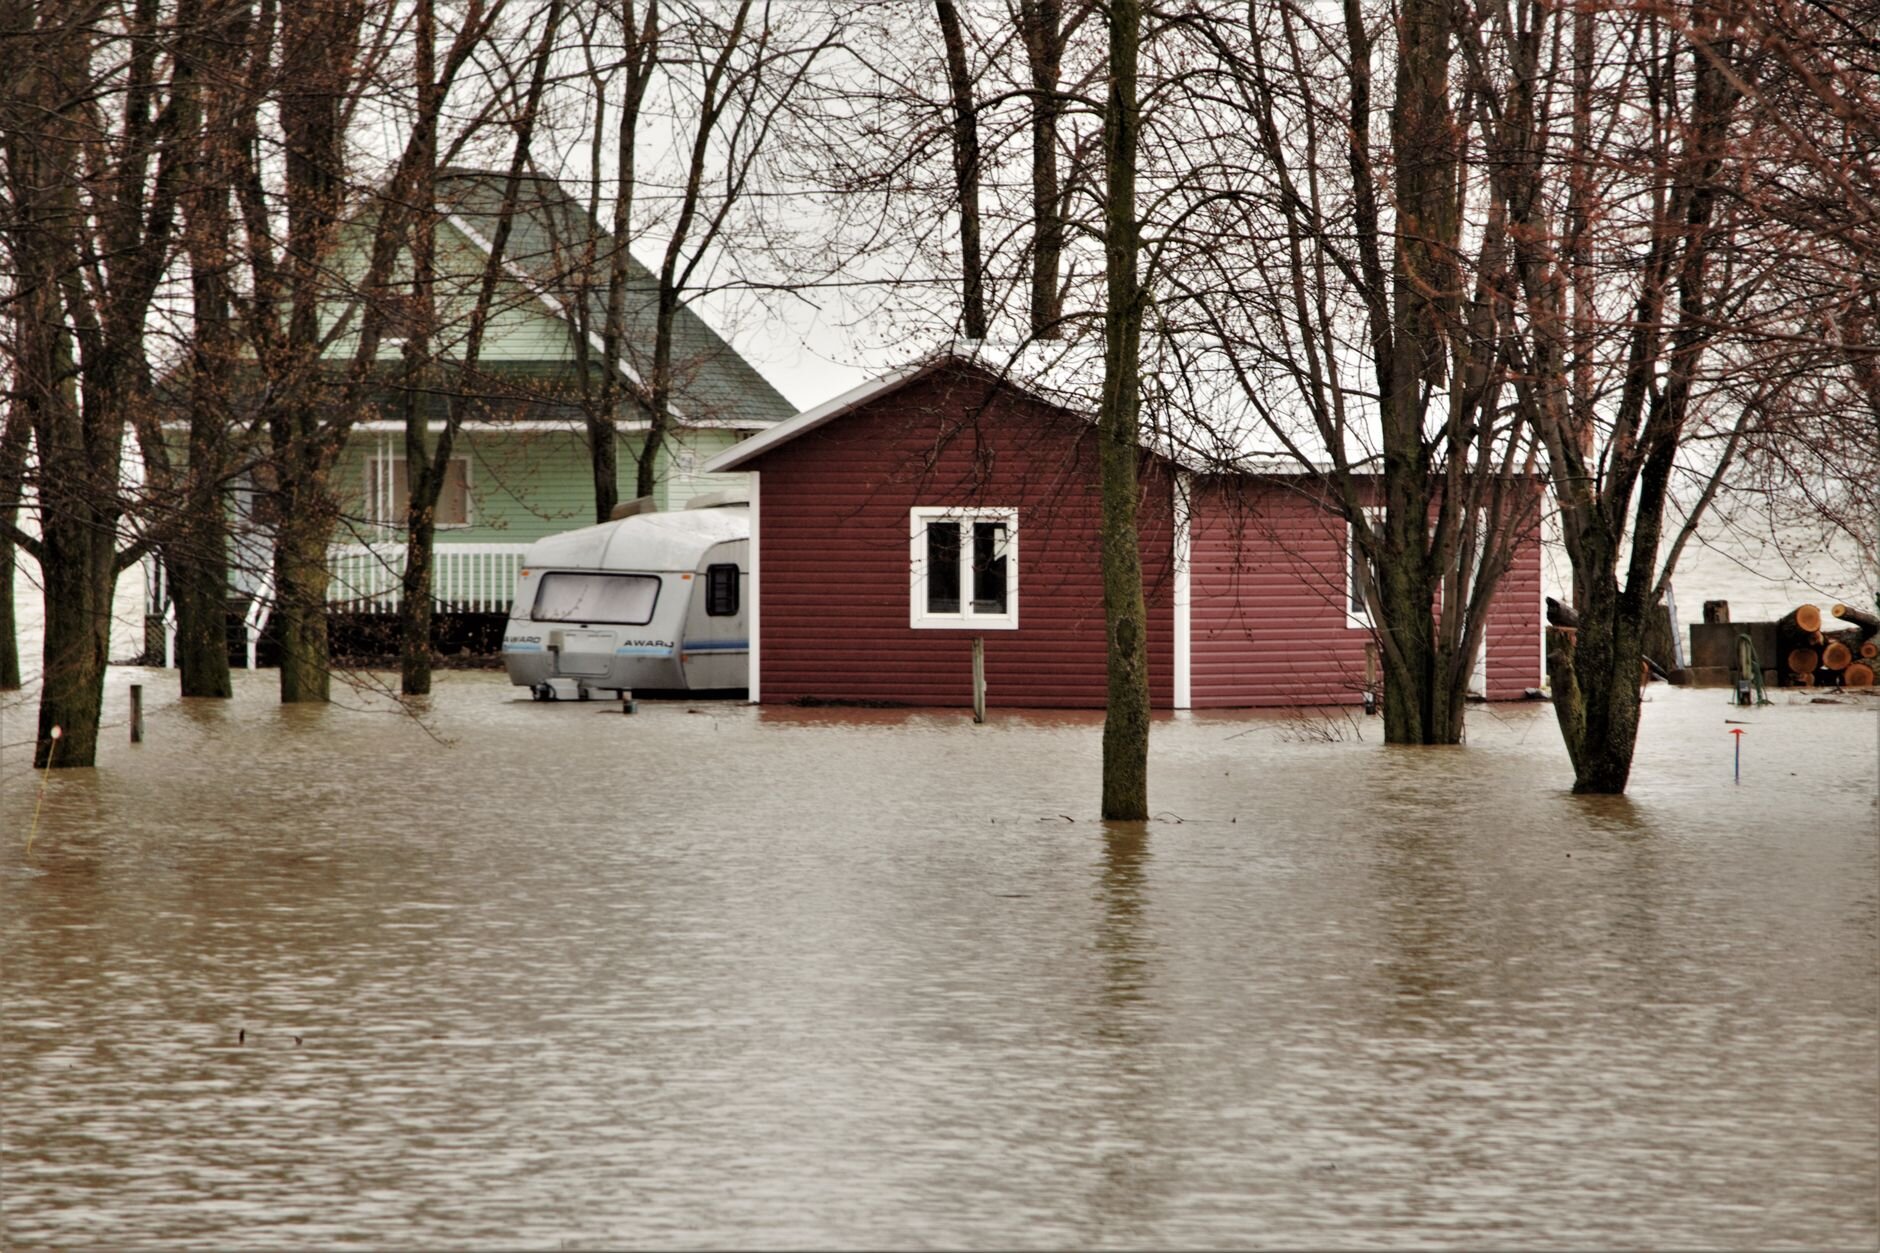
Flood and earthquake damage is excluded from most standard policies. If you live in a higher-risk area, that protection comes from a separate policy or a rider—an add-on that extends what a standard policy covers. Without a rider, rebuilding costs after a major event fall on you.
Hippo's research into insurance rider adoption found that 40% of homeowners carry no riders at all. The most common reason is homeowners believing their base policy already covers enough (32%), with cost second (23%). Working with a licensed agency like Hippo can help you identify and close these coverage gaps.
Why your liability limits deserve a second look
Liability claims against your home insurance policy can get big, making this part of your policy worthy of close examination. If a neighbor seriously injured themselves slipping on your driveway, they could easily bring a claim big enough to exceed your liability limit. Your personal liability provides the legal defense and settlement funds for such claims, up to your limits. So think carefully about the risk of such claims on your property and set your liability limits wisely.
Don’t overlook loss of use
Loss of use—Coverage D part of property and liability coverage—pays for additional living expenses if damage to your home makes it uninhabitable. Several months in a hotel adds up fast and it helps cover those costs, up to your policy limits, while your home is being restored.
In the 2026 Housepower Report, 33% of homeowners said unexpected repairs affected their financial stability, which is worth weighing before you settle on your own limits. If you also insure a vehicle, ask whether you can bundle home and auto insurance with the same carrier.
Proactive protection: preventing claims, not just paying for them
While many insurance companies focus on paying out claims, Hippo can help you prevent them, which in the long run, can save you money and stress. We do that by helping you manage the risks a policy won't cover and avoid having to file a claim in the first place. With Hippo you get:
- Maintenance reminders to help you stay ahead of wear-and-tear damages
- One account to manage your home and auto policies together
- Access to licensed agents who’ll explain what your policy does and doesn't cover
What to do next
- Review your declarations page—the one-page summary at the front of your policy, and check your dwelling and liability limits against your rebuild cost today
- Identify the maintenance you've put off—deferred maintenance can lead to costly repairs, so schedule the top item this week
Still have questions?
Is flood insurance included in my standard policy?
No. Standard homeowners policies exclude flood damage. Flood protection generally comes from a specialized provider or from FEMA's National Flood Insurance Program.
Does insurance cover my old roof?
A policy typically covers sudden damage, like a tree falling through the roof. It doesn't cover roof damage that’s resulted from wear and tear over the years
What is personal liability?
It's the part of your policy that helps pay legal expenses and damages if you're held responsible for someone else's injury or property damage.
How can I lower my premium?
Your deductible—the amount you pay before the policy kicks in—is the most direct way to lower your premium. Bundling multiple policies with one carrier is another way.
Compare home and auto insurance options through Hippo, including auto insurance quotes alongside your home policy review.
Methodology:
Any data referencing the 2026 Housepower Survey and the Insurance Rider Report was collected on September 22, 2025, and conducted by Centiment on behalf of Hippo Insurance Services. The results are based on 1,619 completed surveys. In order to qualify, respondents were screened to be residents of the United States, over 18 years of age, and homeowners. Data is census-balanced, and the margin of error is approximately ±2% for the overall sample with a 95% confidence level. The MOE and confidence level for data filtered by specific demographics (subgroups) may differ from the overall result.
This article is for informational purposes only. The content reflects general homeowner considerations and is not professional advice. It also includes observed trends within the surveyed population and certain additional information compiled from sources not affiliated with Hippo. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.
Sources cited are publicly available and referenced in August 2026.