Water backup and flood coverage
A heavy rainstorm hits and your basement starts taking on water. Whether your insurance pays for the cleanup comes down to one thing: where the water came from. It's easy to assume that the water portion of your standard policy will cover any water entering your home. But that’s not the case.
Your standard homeowners insurance policy typically only covers sudden and accidental internal water damage, such as a burst pipe. For protection against other types of water damage, you need either a water backup endorsement, or flood insurance.
Each type of insurance addresses water damage in a different way, and knowing the difference can determine whether or not your claim is paid.
Key takeaways
- Standard insurance—typically covers sudden and accidental internal water damage, such as a burst pipe
- Water backup is an endorsement—an add-on to your existing homeowners policy, that covers water coming up through sewers, drains, or a failed sump pump
- Flood insurance is a separate policy—it covers surface water moving from the outside in
- Your declarations page tells you what you have—look for a line item labeled “water backup” or “sump pump overflow”
What is water backup insurance?
Water backup is an optional endorsement you can add-on to your homeowners insurance policy. Standard home insurance covers water damage from many internal sources, but not from water backing up through sewers, drains, or sump pump overflows. This endorsement fills that gap.
Sewer and drain failure
A sewer backup happens when the public sewer system or your private lateral line, the pipe running from your house to the public sewer, gets blocked or overwhelmed. That forces wastewater back into your home through toilets, sinks, or floor drains. Because this water is often contaminated, cleanup involves more than drying the space. Drywall and flooring usually need to be removed.
Without a water backup endorsement, you'd pay for that cleanup yourself. Adding it to your policy puts those costs on your insurer instead, up to the limit you choose.
Sump pump overflows
Sump pumps keep basements dry by pumping out groundwater, but they do fail. A mechanical problem or a power outage during a storm can stop a pump mid-storm, and the pit overflows quickly. If your basement is finished, that water reaches electronics, furniture, and structural elements. Water backup insurance is built for these types of failures too..
What doesn’t water backup insurance cover?
Every insurance company is different, so it’s always wise to check with your carrier and individual policy to understand what is and isn’t covered by your water backup coverage.
Generally, though, several instances of flooding and water damage aren’t covered by this portion of your policy, no matter who the insurer is. These include:
- Intentional acts that cause flooding inside your home are never covered.
- Sometimes, water backup policies won’t cover the replacement costs or repair of the source of the overflow, such as broken appliances or plumbing lines.
- The cause determines whether or not it’s covered. If an issue outside normal wear and tear, such as owner negligence, caused the overflow, it won’t be covered.
- Water damage caused by a natural disaster — such as a flood, thunderstorm, or hurricane — is excluded.
If you’re worried about natural disasters, get a separate flood or hurricane insurance policy. This may even be required in some states and high-risk areas, especially if a mortgage loan finances the property.
What is flood insurance?
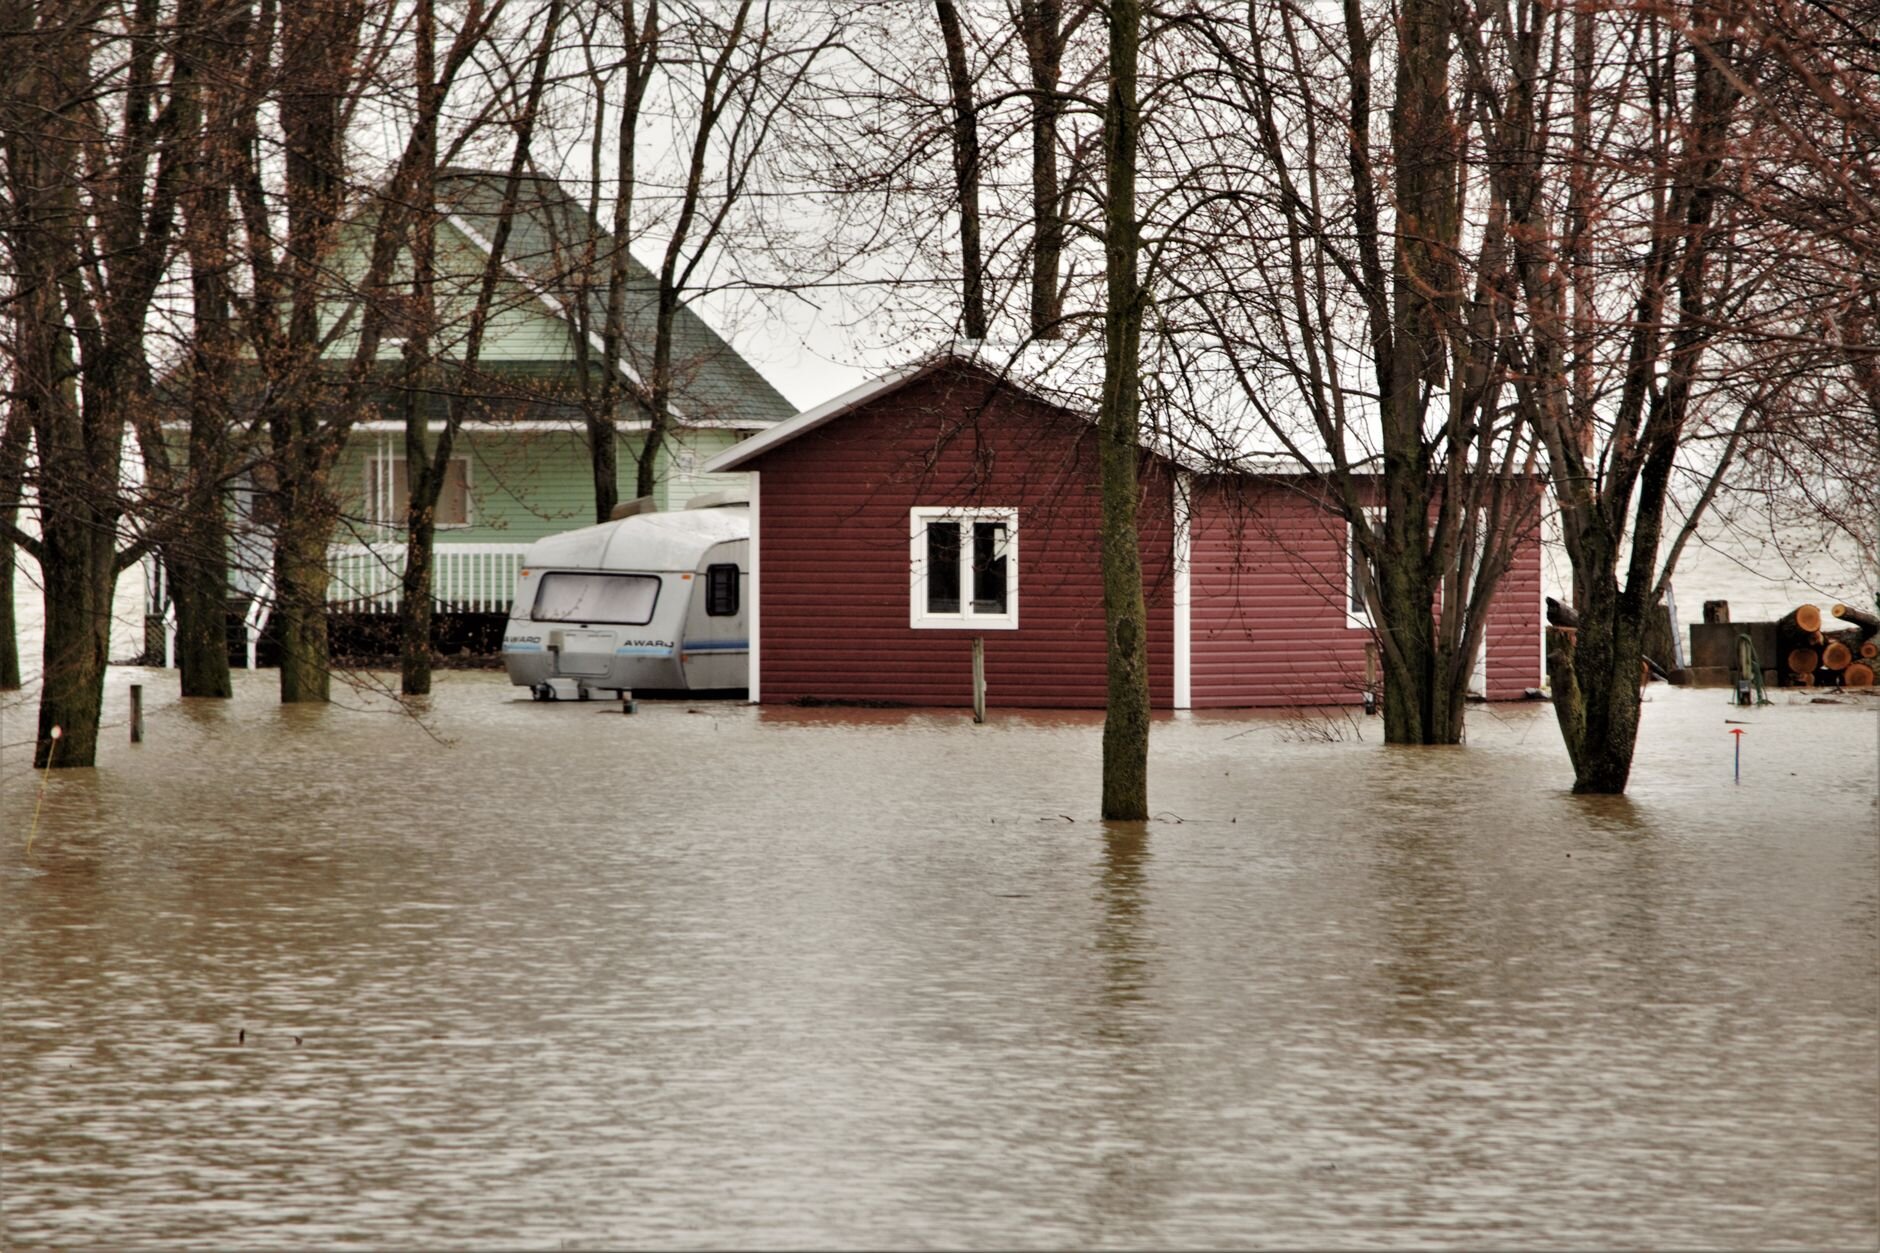
Flood insurance is an optional type of property insurance that can cover both your home’s structure and your belongings in it. Flood insurance protects you against water damage resulting from heavy or long lasting rain, melting snow, storm surges along the coast, clogged storm drains, and levee dam failures.
Water backup vs. flood insurance
The difference comes down to the direction the water moves. Water backup involves water coming up through your pipes, or water that never got pumped out. Flood insurance covers surface water moving from the outside in: overflowing rivers, heavy rain pooling against your foundation, or storm surge.
And neither policy covers the other policy’s type of water damage. You can't rely on a water backup endorsement for a flash flood, and you can't rely on flood insurance for a clogged sewer line.
One is an add-on, the other is a separate policy
If you wanted water backup insurance, you’d attach it to your existing home insurance policy. Flood insurance on the other hand, is a separate, standalone policy. If your home sits in a high-risk flood zone, your mortgage lender will likely require it. If you live outside a flood zone, it's still worth a look.
Water backup vs. flood insurance at a glance
Feature | Water backup endorsement | Flood insurance |
|---|---|---|
Where the water comes from | Internal drains, sewers, sump pumps | Surface water, overflowing bodies of water |
How you buy it | Optional add-on to home insurance | Separate, standalone policy |
What it's designed for | Mechanical or plumbing failure | Natural disasters and rising water |
What it costs | Varies by home, limit, and carrier | Varies by flood zone risk |
Getting a quote with the policy you really need
Checking what you already have is the first step toward avoiding a surprise bill after a storm. Then assess your situation carefully and get some new quotes to better understand your options.
- Review your declarations page—the summary at the front of your policy. Look for a line item labeled water backup or sump pump overflow. If it isn't there, you don't have this protection.
- Weigh your local risk—a finished basement, an older sewer lateral, or an area that gets heavy seasonal rain all point toward a higher limit.
- Request a new home insurance quote— and include the water backup endorsement in the request, and use the same endorsement limits on every quote so you're comparing the same thing.
How to proactively prevent water damage
Having the right water insurance goes a long way, but so does avoiding water damage altogether. Make a note to test your sump pump every spring and keep your gutters clear throughout the year so that water drains well when a heavy rain occurs. To avoid water backups, be careful about what you flush down the toilet—stick to toilet paper only.
Smart leak sensors are another way to stay ahead of water damage. They catch moisture in a basement long before it turns into a repair. Pairing prevention and water damage maintenance with the right endorsements covers both sides of this risk: the failures you can prevent, and the ones you can't.
Recovering from water damage
If water damage occurs, some important first steps must be taken immediately. These can help mitigate further damage and get the ball rolling on repairs.
First, you'll want to take photos to document any damages and their causes. In some cases, you may need your insurance agent or an inspector to examine the damage to help determine the official cause. Any photos or information you gather will be helpful when you submit your claim for coverage.
While your claim is taking place, focus your efforts on preventing further damage. This can mean removing standing water or moldy surfaces so your home can start drying out. Install dehumidifiers and/or fans, open windows, and regularly clean to prevent more damage or mold.
Water backups—and the damage they can cause—can wreak havoc on your home and personal property, often with little to no warning. Unfortunately, these damages aren’t always covered by a standard homeowners insurance policy. With the right home insurance water backup endorsement, though, you can ensure that your property is always protected against unexpected water events and damage.
What to do next
- Test your sump pump by pouring a bucket of water into the pit to ensure it triggers correctly
- Locate your main water shut-off valve so you can act quickly if a pipe bursts
- Review your current policy limits with a licensed agent and consider a water backup endorsement or flood policy with limits that match the value of your home and belongings
Frequently asked questions
Do I need water backup if I don't have a basement?
Yes, water backup is still worth considering even if you don’t have a basement. Homes on a slab can back up through floor drains, showers, and toilets, and that water damages flooring and cabinetry the same way.
Does homeowners insurance cover mold?
Standard homeowners insurance policies may cover mold remediation only if the mold resulted from a covered cause of water damage, like a burst pipe. They generally don't cover mold caused by long-term neglect or humidity.
Is water backup the same as service line insurance?
No, water backup and service line insurance are different. Water backup covers the damage inside your home. Service line protection covers the repair of the underground pipes running from the street to your house.
What is a sump overflow?
A sump is a pit or hole, usually located at the lowest point in your basement, where excess water can collect. This water can be removed with a sump pump, but if your pump fails or too much water collects, it can overflow and back up into your property.
What does water backup mean?
Water backup occurs when a drain, pump, gutter, or sewer line heading away from your home fails — due to clogs, heavy rain, or debris — allowing water to flow backward into the property. This water backup can result in clean or unsanitary water coming up through your toilets, sinks, drains, or even up through your yard, causing damage to your property.
How do I measure my sump water level?
If you want to determine how much water is currently in your sump or check that your sump pump is working appropriately, some experts recommend pouring a bucket of water into the pit. This is often enough to trigger the pump to kick on and remove the water. If the sump pump doesn't kick on, damage or a clog may prevent it from working in a real emergency.
How full should a sump tank be?
It’s normal for your sump pump to always retain a few inches of water in the pit. Even if your sump pump hasn’t run a cycle recently, it might still keep around 2” to 3” of water in the bottom. This isn’t enough to trigger the pump, and as long as the level doesn’t continuously increase or reach the float switch, it doesn’t indicate a problem.
Through our network of 70+ trusted carriers, Hippo can help you find the best quotes and coverage options available for water back up and flood insurance. Get your free quote in about 60 seconds at hippo.com
This article is for informational purposes only and was compiled from sources not affiliated with Hippo. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.
Sources cited are publicly available and referenced in August, 2026.