How long do claims stay on your record?
Home insurance claims stay on your record for five to seven years. That's the short answer. And it generally holds true whether you switch carriers or stay put.
But the long answer is more complicated. Insurers track loss history in a shared database called the Comprehensive Loss Underwriting Exchange, or CLUE. And a settled claim is never removed from the CLUE database simply because it was closed.
So in effect, the CLUE database serves as a historic record of your past losses and claims. It’s where insurers go to understand your loss history and determine a price when you request a quote. Whether you're pulling new homeowners insurance quotes or reviewing the policy you already have, your record on CLUE travels with you.
Here's how long claims last, what the CLUE report shows, and what you can do about what's on it.
Key takeaways
- A claim stays on your file for five to seven years—and a new insurer can see it even after you switch
- The CLUE report is where your loss history lives—it lists the date, type and amount paid for each claim
- You can pull your own CLUE report—it’s allowed once every 12 months at no cost under the Fair Credit Reporting Act
- Frequency reads differently than severity—several small claims and one large loss are not weighted the same way
- A zero-dollar claim can still appear—a claim that paid out nothing may still show that an incident happened
How the claims record timeline works
The standard 5 to 7 year window
As explained in the article, "Will My Homeowners Insurance Go Up If I File A Claim?," a claim stays on your record for five to seven years. During that time, insurers look at your home insurance claims history to assess the risk of the property: and if you change insurance carriers, your new insurer can see that activity too. If you're pulling auto insurance quotes at the same time, note that those run on a separate record: your driving history, not your home's.
Why the timeline varies by state
The five to seven year window is the national norm, and state law can change how long information stays available or how an insurer may use it. Your state's Department of Insurance is the place to confirm the rules where you live. Either way, plan on a large property loss sitting on your profile for years rather than months. Make sure you factor that in when you compare home insurance rates across carriers.
What is a CLUE report and why does it matter?
How insurers use loss history
Insurers use specialized databases like the CLUE to track property loss history. A CLUE report affects the premium you're quoted, because it gives the insurer a snapshot of every claim you’ve filed, as well as all claims filed against a property you want to insure.
What a CLUE report contains:
- The date, type, and amount paid for every claim filed by a homeowner, or against a property
- Both property-specific and individual homeowner history
CLUE helps determine your overall risk profile for insurers. And you can request a free copy of your CLUE report every 12 months under the Fair Credit Reporting Act.
Factors that influence your insurance record
Claim frequency vs. severity
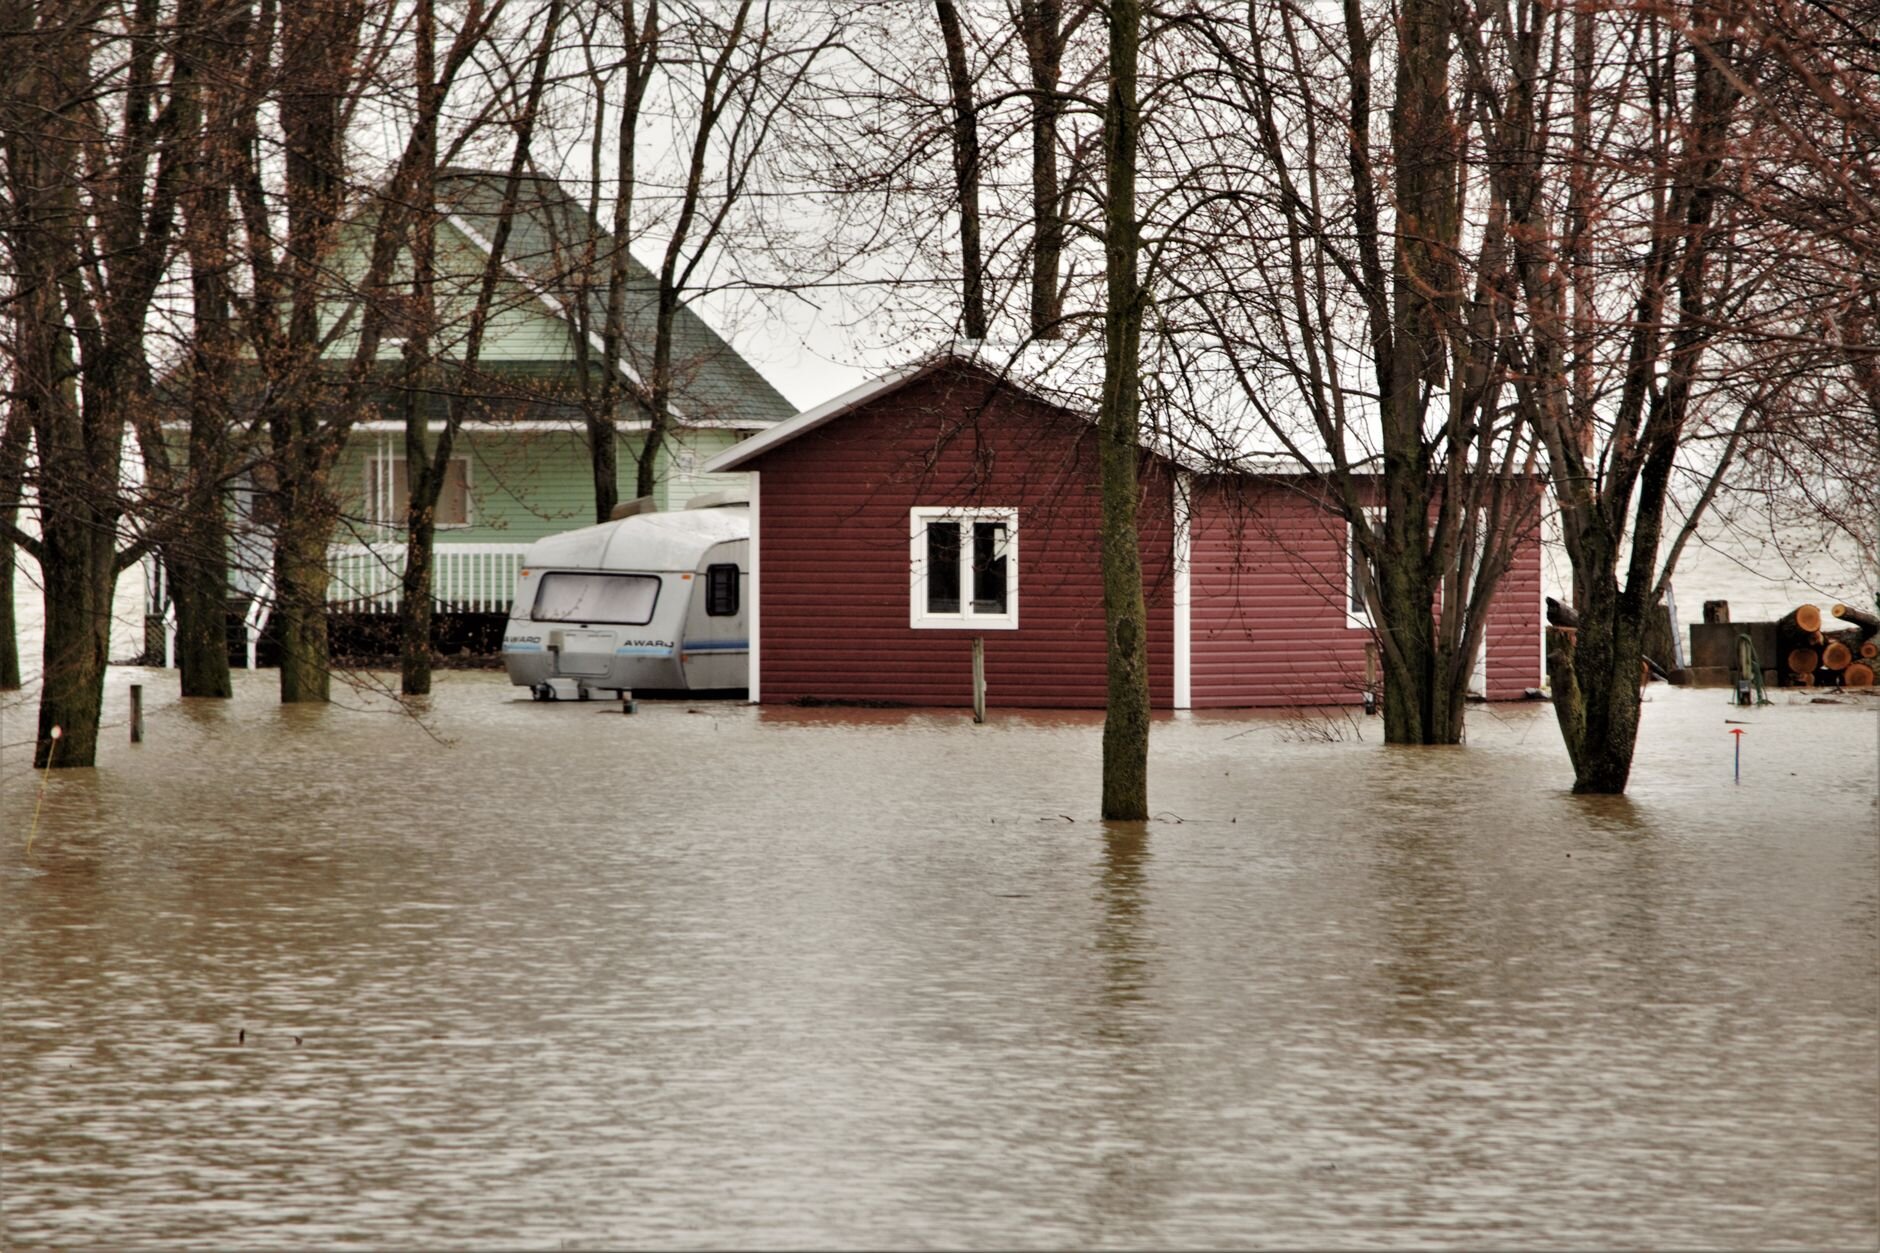
Insurers look at the difference between one major event and a pattern of smaller claims. A single claim for wind damage after a storm is read differently than three claims for minor leaks. In fact, filing multiple claims makes higher premiums likely, and it can affect your ability to get home insurance at all.
The impact of zero-dollar claims
An inquiry, which is essentially any contact with your insurer to ask about coverage for a potential claim, can appear on your CLUE report even when you don’t file a claim and your insurer pays nothing. These are considered zero-dollar claims. They don't represent a financial loss for your insurer, but they do show that an incident happened. For that reason, it's worth understanding the claims process before contacting your insurer about damage that’s below your deductible.
How to proactively manage your insurance history
Preventive maintenance strategies
A clean history is easier to keep when you prevent the incident in the first place. Address the small things—an aging water heater, worn roof shingles, a slow drip under a sink—and you can avoid having to file a claim in the first place.
What to do next
- Review your CLUE report annually to ensure all listed claims are accurate
- Keep your home in good standing and avoid frequent claims by staying on top of maintenance tasks
- Pull quotes with similar coverage options from other carriers before renewing; rates can change, so it’s worth seeing how your current policy compares
When you check your home insurance rate against other carriers, that’s a perfect time to ask about other options like pet insurance, or if they can bundle auto insurance. For questions about your coverage options, talk to your Hippo agent. We’re here to help. Reach us at (650) 426-0546 or [email protected].
And remember, you can compare quotes from 70+ carriers in about 60 seconds at hippo.com
Frequently asked questions
How do I know if a claim has fallen off my record?
You'll know a claim has fallen off your record by reading your CLUE report. If there’s a claim on your record that’s older than the required holding period where you live, you can file a dispute to correct it.
Does a claim on my old house affect my new one?
Yes, a claim on your old house can affect your new house. The CLUE report tracks both the property and the individual, so a history of claims at a previous home may follow you and affect what you're quoted.
Methodology
The survey data in this article comes from Hippo's 2026 Housepower Report, published January 15, 2026. The survey was conducted by Centiment on behalf of Hippo Insurance Services and completed on September 22, 2025. The results are based on 1,619 completed surveys. To qualify, respondents were screened as residents of the United States, aged 18 or older, and homeowners. The data is census-balanced, and the margin of error is approximately ±2% for the overall sample at a 95% confidence level. The margin of error and confidence level for data filtered by specific demographics (subgroups) may differ from the overall result.
This article is for informational purposes only. The content reflects general homeowner considerations and is not professional advice. It also includes observed trends within the surveyed population and certain additional information compiled from sources not affiliated with Hippo. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.
Sources cited are publicly available and referenced in August, 2026.