Condo Insurance Explained: What HO-6 Covers (and What It Doesn’t)
Condo insurance doesn’t typically cover what a homeowners insurance policy covers, and that gap is where a lot of condo owners get caught off guard. Your homeowners association (HOA) typically insures the building and the shared areas, while an HO-6 policy typically covers what’s inside your unit, your belongings, and your personal liability. When a pipe bursts in the building’s lobby at 2 a.m. or a guest slips on your kitchen floor, knowing which policy covers which loss, can help protect you from a big bill.
Here's what an HO-6 policy covers and excludes, how it works alongside your HOA's master policy, whether you're required to carry one, and how much coverage you may need—so you know what you're buying when considering a quote.
Key takeaways
- Your HOA insures the building, you insure your unit—the line between the two is determined by your HOA’s master policy
- An HO-6 policy has five parts—your interior, your belongings, your liability, guest medical, and temporary living costs
- Your lender or HOA will probably require an H0-6 policy—and even if they don’t, it’s probably worth getting one so you’re not exposed to unexpected losses
- Set your dwelling limit against the cost to rebuild your interior—including every upgrade and renovation you paid for
- Floods and earthquakes typically aren’t covered—most standard HO-6 policies exclude floods and earthquakes, so those need separate insurance
Quick answer: what condo (HO-6) insurance covers
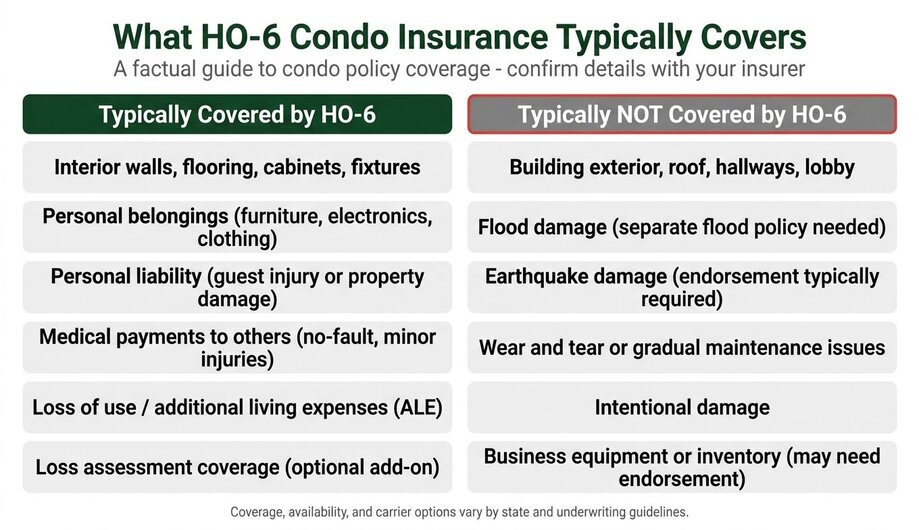
Condo insurance, or an HO-6 policy, typically covers:
- Your personal belongings, liability, and the interior of your unit (including any upgrades you’ve made)
- Additional living expenses if a covered loss makes your unit unlivable
Your HOA’s master policy typically covers your building’s structure and shared, common areas. The exact line between what your HOA covers versus what your H0-6 policy covers is determined by your HOA’s master policy type and governing documents.
What is condo insurance (HO-6 insurance)?
Condo insurance is a policy designed for people who own a unit inside a larger building or community. The standard form is called an HO-6 policy. Because you don’t own the entire structure, the way a single-family homeowner does, your coverage is built to handle the part of the property you actually control: the inside of your unit, the things you keep there, and your responsibility to other people.
Why it’s different from homeowners insurance
A standard homeowners policy (often an HO-3) covers the entire dwelling, from the roof down to the foundation, plus your belongings and liability. A condo policy strips out the building structure because that part is usually insured collectively through your HOA. In short, homeowners insurance covers a whole house you own outright, while condo insurance covers your slice of a shared building. That difference shapes how the policy is priced and what it protects.
What an HOA master policy is (and why it matters)
Your association carries a master policy that protects the shared parts of the property, funded through your HOA dues. It typically covers the building’s exterior, the roof, hallways, lobbies, elevators, and amenities like a pool or gym.
The catch is that master policies come in different forms, and where the master policy stops is exactly where your HO-6 policy needs to begin. Start with the master policy's coverage type. It's what tells you how much condo insurance you actually need.
Quick definitions (unit, common areas, master policy, loss assessment)
Your unit is the interior space you own and live in. Common areas are the shared spaces everyone uses, like hallways, stairwells, and amenities. The master policy is the association’s insurance on the building and common areas. Loss assessment is a charge your HOA can pass to unit owners when a covered loss exceeds the master policy's limits.
What does condo insurance cover?
An HO-6 policy is usually built from several standard coverage parts. Here’s what each one typically does and why it matters for a condo owner.
Dwelling coverage (Coverage A): what “inside your unit” typically means
Coverage A on an HO-6 policy protects the parts of your unit you’re responsible for, which often includes interior walls, flooring, cabinets, built-in appliances, fixtures, and any upgrades you've paid for yourself (your policy may call these improvements and betterments).
If you remodeled the kitchen with quartz counters and custom cabinetry, that upgrade typically falls to your HO-6, not the master policy. How much of the interior you’re responsible for varies with the master policy type, so set this limit based on what it would cost to rebuild your unit’s interior and finishes.
Personal property (Coverage C)
This covers your belongings: furniture, electronics, clothing, kitchenware, and the everyday items you’d have to replace after a covered loss like a fire or theft.
Most policies let you choose between replacement cost (the cost to buy an item new) and actual cash value (the current value of an item). If you want a refresher on how those valuation methods differ, read our article on actual cash value vs replacement cost. Keep in mind that valuables such as jewelry, bikes, cameras, and art often carry special limits, so you may want to schedule those items separately to insure their full value.
Personal liability (Coverage E)
Liability coverage helps protect you if you’re found legally responsible for someone else’s injury or property damage. If a guest trips and breaks an arm in your unit, or your overflowing bathtub damages the unit below, this coverage can help with legal costs and settlements up to your limit. Owners often set this limit at $300,000 or more, and add an umbrella policy when they want higher limits.
Medical payments to others (Coverage F)
This is a smaller, no-fault coverage that can pay for minor medical bills if a guest is hurt in your unit, regardless of who was at fault. It’s designed to handle small injuries quickly and may help avoid a larger liability claim. Limits are typically modest, often a few thousand dollars.
Loss of use / additional living expenses (ALE)
If a covered loss makes your unit temporarily uninhabitable, loss of use coverage can help pay for added costs like a hotel, a short-term rental, and meals while repairs happen. It’s meant to cover the difference between your normal living costs and the higher costs you face while displaced, so you’re not paying out of pocket to live somewhere else after a fire or major water loss.
Loss assessment coverage (common HO-6 add-on)
When a covered loss to shared property exceeds the master policy’s limits, the HOA can divide the shortfall among unit owners as a special assessment. Loss assessment coverage helps pay your portion, up to the limit you select.
For example, if a fire damages the shared roof and the repair bill exceeds the master policy, your share of the assessment may be covered. It's usually a small add-on relative to what an assessment can cost.
What condo insurance doesn’t cover (common exclusions)
No policy covers everything, and knowing the gaps up front helps you avoid a denied claim later. These are the exclusions condo owners run into most often.
Floods and earthquakes (often separate policies or endorsements)
Standard HO-6 policies typically exclude flood and earthquake damage. If your building sits in a flood-prone area or a seismic zone, you may need separate flood insurance or an earthquake endorsement (an add-on to your existing policy) to be protected. These risks are usually handled outside the base policy, so it’s worth asking about them when you shop.
Wear and tear, maintenance, pests, and mold (often limited or excluded)
Insurance is built for sudden, accidental events, not for gradual problems. Routine wear and tear, deferred maintenance, insect or rodent damage, and mold from a long-term leak are commonly excluded or tightly limited. Staying ahead of small problems is what keeps them from becoming uncovered losses. Check under sinks, clear gutters, and replace aging supply lines before they fail, since a small ignored leak can turn into an uncovered repair.
Intentional damage
Damage you cause on purpose isn't covered. Insurance responds to accidents and unexpected events, not deliberate acts, so intentional damage to your unit or someone else’s property falls outside the policy.
Business activity in the home (may need an endorsement)
If you run a business out of your condo, your standard policy may not fully cover business equipment, inventory, or liability tied to clients visiting your unit. A home-business endorsement or a separate policy may be needed. If you work from home with little more than a laptop, the exposure is smaller, but it’s still worth confirming.
What your HOA covers vs what your HO-6 covers
Where your HOA’s coverage ends and yours begins depends on the master policy and your governing documents, so the difference may vary. Use this table as a general guide, then confirm the specifics with your HOA.
| Category | Typically covered by HOA master policy | Typically covered by HO-6 condo insurance |
| Building structure (roof, exterior walls) | Yes (common areas; varies by policy) | No |
| Hallways, lobbies, amenities | Yes | No |
| Your unit’s interior walls and fixtures | Varies (bare walls vs all-in) | Often yes for the inside of the unit |
| Upgrades/remodels (betterments) | Often no / varies | Often yes (choose adequate dwelling limits) |
| Personal belongings (furniture, electronics) | No | Yes (personal property) |
| Personal liability | No | Yes |
| Guest medical payments | No | Yes |
| Temporary living expenses | No | Yes (loss of use) |
| Water damage | Varies; sudden/accidental may be covered, maintenance issues often not | Often covered if sudden/accidental; exclusions apply |
| Loss assessment (shared repairs after covered event) | Master policy may cover building; assessments can still happen | Often yes with loss assessment coverage (limits vary) |
Bare walls vs single entity vs all-in master policies
A bare walls master policy covers only the building shell, leaving interior walls, flooring, and fixtures to each unit owner. A single entity policy covers the building plus original fixtures in your unit as first installed, but not your personal upgrades. An all-in policy covers both the building and all fixtures, whether original or upgraded. The type of policy your HOA carries determines how much dwelling coverage you need on your HO-6.
How to confirm what your HOA covers
Ask your HOA board or property manager for the master policy declaration page, the bylaws, and the covenants, conditions, and restrictions (CC&Rs). Look for the coverage type stated (bare walls, single entity, or all-in), the master policy deductible, and any coverage limits for common areas. That information becomes your baseline for setting your own HO-6 coverage limits.
Is condo insurance required?
Condo insurance isn’t always legally required, but your mortgage lender or your HOA may require you to carry one.
If you have a mortgage, your lender may require it
Most mortgage lenders require you to carry condo insurance as a condition of the loan, since it protects the lender’s interest in the unit’s interior and your ability to repair or replace damaged property after a covered loss.
Your HOA may require it, too
Many associations require owners to maintain an HO-6 policy (often with minimum liability limits) and provide proof of insurance. This helps protect the community if an incident in one unit causes damage or injury.
Even if your lender and HOA don’t require an HO-6 policy, carrying one can be a straightforward way to protect yourself from a large out-of-pocket loss. Without condo insurance, a fire, theft, or water damage event could mean replacing all your belongings at your own expense, covering legal costs if a guest is injured, or paying your share of an HOA special assessment with no help from an insurer.
How much condo insurance do you need?
The right amount of condo insurance depends on what your HOA’s master policy covers, how much your belongings are worth, and your exposure to liability risk.
A good starting point is to match your dwelling coverage to what it would cost to rebuild the inside of your unit (including upgrades), determine personal property based on a realistic inventory, and select liability limits you’d feel comfortable carrying if a serious claim happened.
Choosing dwelling coverage (based on HOA policy and your improvements)
Set your dwelling (Coverage A) limit based on what you’re responsible for inside the unit under your HOA’s master policy, plus any improvements or betterments you’ve made. If the association has a “bare walls” policy, you may need more dwelling coverage than you would under an “all-in” policy.
Choosing personal property coverage (inventory method)
Start with an inventory of major categories, including furniture, electronics, clothing, kitchen items, sporting equipment, and valuables. Add up realistic replacement costs (not garage-sale prices), then choose a Coverage C limit that reflects that total. If you own high-value jewelry, art, or camera gear, consider scheduling those items for broader protection.
Choosing liability coverage (risk-based)
Liability is the one limit worth revisiting as your savings grow. Many condo owners choose at least $300,000, and some opt for $500,000 or more, especially if they have meaningful savings, investments, or other assets to protect.
Deductibles: how to pick one
A higher deductible can lower your premium, but it also increases what you pay out of pocket on a claim. Choose a deductible you could realistically afford after an emergency, and check your HOA's master policy deductible too, since a large one raises the odds of an assessment landing on you.
Optional coverages to consider
Depending on your condo and your risk profile, you may want add-ons such as loss assessment coverage, water backup, identity theft protection, valuable items coverage (scheduled personal property), or earthquake coverage (where available).
How much does condo insurance cost?
Condo insurance is generally less expensive than a standard homeowners policy because you’re insuring the interior of your unit rather than an entire structure. That said, your premium varies depending on where your building is located, what coverage limits you choose, and several other factors.
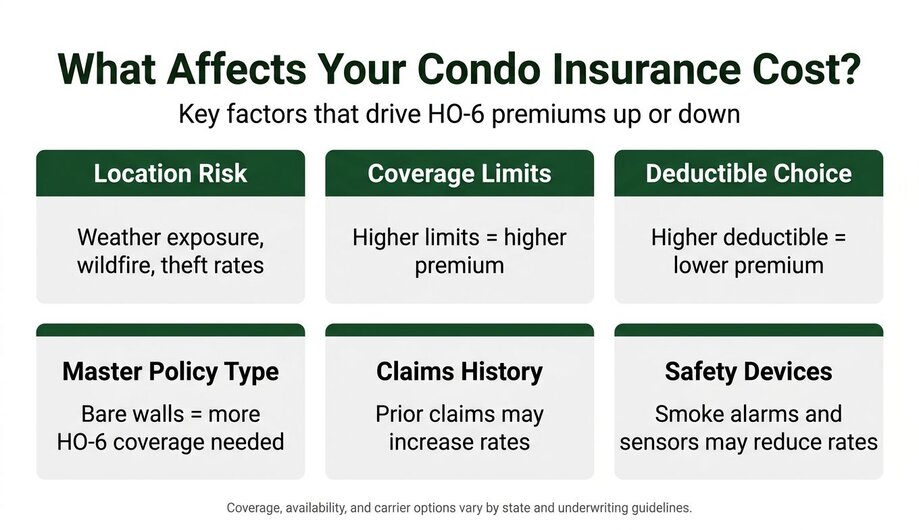
© Hippo Insurance Services. Key factors that typically affect HO-6 condo insurance premiums.
Main factors that typically affect price
Pricing is usually influenced by location, the age and construction type of the building, your coverage limits (dwelling, property, liability), deductible, endorsements (like water backup), and your prior claims history.
Ways to save on condo insurance
You can often save by bundling policies, raising your deductible (if you can afford it), improving home safety (like smoke alarms or smart leak detection), keeping good credit in states where insurers are allowed to use it, and shopping around periodically.
How to get a condo insurance quote (and what you’ll need)
Shopping for condo insurance is straightforward once you've gathered the right information.
Information to gather before you shop
Before you start comparing quotes, pull together these key pieces of information:
- Your HOA’s master policy deductible and the declaration page to confirm coverage type (bare walls, single entity, all-in)
- The estimated square footage of your unit
- A rough inventory of your personal belongings with their replacement values
- A list of any upgrades or improvements you’ve made to your unit
- The address of your building
Having this information ready makes the quoting process faster and helps you choose coverage limits that actually reflect what you’re responsible for.
What to compare across quotes
When choosing a condo policy look at more than just price. Consider these factors:
- What the deductible is
- Coverage type—replacement cost vs actual cash value for personal property
- Whether loss assessment and water backup are included or available as add-ons
- How the carrier handles claims
- What the coverage limits are for dwelling, personal property, and liability
A slightly higher premium may come with meaningfully better protection, so compare request quotes with the same coverage selections so you can do a one to one comparison.
Why Hippo
Hippo can help you compare quotes from a network of carriers, so you get multiple options in one place rather than submitting separate applications. The quoting process takes about 60 seconds online. If you'd rather talk it through, licensed agents are available to help. Get a free quote in about 60 seconds at hippo.com.
Condo insurance FAQs
Does condo insurance cover water damage?
Condo insurance may cover sudden and accidental water damage (like a burst pipe). It typically won’t cover long-term leaks or a backed-up drain unless you add a water backup endorsement.
Does condo insurance cover theft?
Yes, personal property coverage typically covers theft of belongings from your unit. Keep in mind that some categories of valuables, like jewelry, cameras, and bicycles, are usually capped at a few thousand dollars under a standard policy. If you own high-value items, you may want to schedule them separately for broader protection.
Does condo insurance cover my neighbor’s unit if I cause damage?
It depends on the situation. If you’re found legally responsible for damage to a neighboring unit, your personal liability coverage may help pay for repairs and legal costs. For example, if an overflowing bathtub causes water damage to the unit below, liability coverage can come into play. Whether and how much is paid depends on your policy limits, the cause of the damage, and whether legal responsibility is established.
What’s the difference between HO-6 and renters insurance?
An HO-6 policy is designed for condo owners and typically includes dwelling coverage for the interior of your unit, in addition to personal property, liability, and loss of use. Renters insurance is for tenants who don’t own the property, so it doesn’t include dwelling coverage. If you own your condo unit, you need an HO-6, not renters insurance.
What’s loss assessment coverage and do I need it?
Loss assessment coverage is an optional add-on to your HO-6 policy that helps pay your share of a special assessment from your HOA after a covered loss. For example, if a hailstorm damages a shared amenity like the parking garage and the repair cost exceeds the master policy’s limits, the HOA may divide the remaining costs among unit owners. Loss assessment coverage can help you pay that bill, up to your selected limit. It's usually a small add-on, and it matters most in older buildings or where the master policy limits are thin.
Hippo helps make home insurance easy. Through our network of 70+ trusted carriers, we’ll find you a great quote and coverage options available. Get a free quote in about 60 seconds at hippo.com.
This article is for informational purposes only and was compiled from sources not affiliated with Hippo. While we believe this information to be reliable, we do not guarantee its accuracy or completeness. For any insurance-related decision, please consult your licensed insurance producer.